Updated: October 2026. Since 1 January 2026, food in restaurants has been subject to 7 % VAT (Mehrwertsteuer). This applies in the restaurant just as it does for pickup and delivery. Drinks stay at 19 %. Sounds like a simple rule, and for a single schnitzel it is.
It gets tricky with set menus. Pizza with cola for 12,90 €, a lunch special with a drink, brunch at a fixed price: here two tax rates are hidden in one price, and you have to split it. In 2025 the Federal Fiscal Court (Bundesfinanzhof) made clear once again how this works.
We have been setting up ordering systems for restaurants for many years, first as a GloriaFood partner, today with eatbase. By the time the first set menus are created at the latest, the tax question comes up. So here is everything in one place, with sample calculations and the sources.
The legal situation in 2026 in brief
The basis is § 12 (2) no. 15 of the German VAT Act (Umsatzsteuergesetz, UStG). Under this, “restaurant and catering services, with the exception of the supply of drinks” are taxed at the reduced rate. It was introduced by the Tax Amendment Act 2025 (Steueränderungsgesetz 2025), which the Bundesrat approved on 19 December 2025. The law does not include an end date.
For context: in 2024 and 2025, 19 % applied to food eaten on site, and only food for takeaway or delivery had 7 %. This distinction is now gone for food. For some drinks, however, it still exists.
| What | on site | Pickup or delivery |
|---|---|---|
| Food | 7 % | 7 % |
| Soft drinks, juice, beer, wine | 19 % | 19 % |
| Milk and milk drinks with at least 75 % milk | 19 % | 7 % |
| Tap water | 19 % | 7 % |
For milk drinks, the recipe counts: the reduced rate for takeaway sales only applies from 75 % milk content in the finished drink. Oat or almond drinks do not count as milk.
Why one set menu has two tax rates
For VAT purposes, a set menu is not a product of its own. The Federal Fiscal Court explicitly confirmed this for value meals of burger, fries and a drink: there are two supplies, the food at 7 % and the drink at 19 %. So your menu price must be split between both rates.
If you simply book the whole menu at 7 %, you pay too little tax. If you book everything at 19 %, you give money away. Either way, it will come to light in a tax audit (Betriebsprüfung) at the latest.
The rule: split by individual selling prices
The tax authorities generally require the split to follow the ratio of the individual selling prices (section 10.1 (11) of the VAT Application Decree, UStAE). Each component gets the same share of the menu price as it has of the sum of the individual prices.
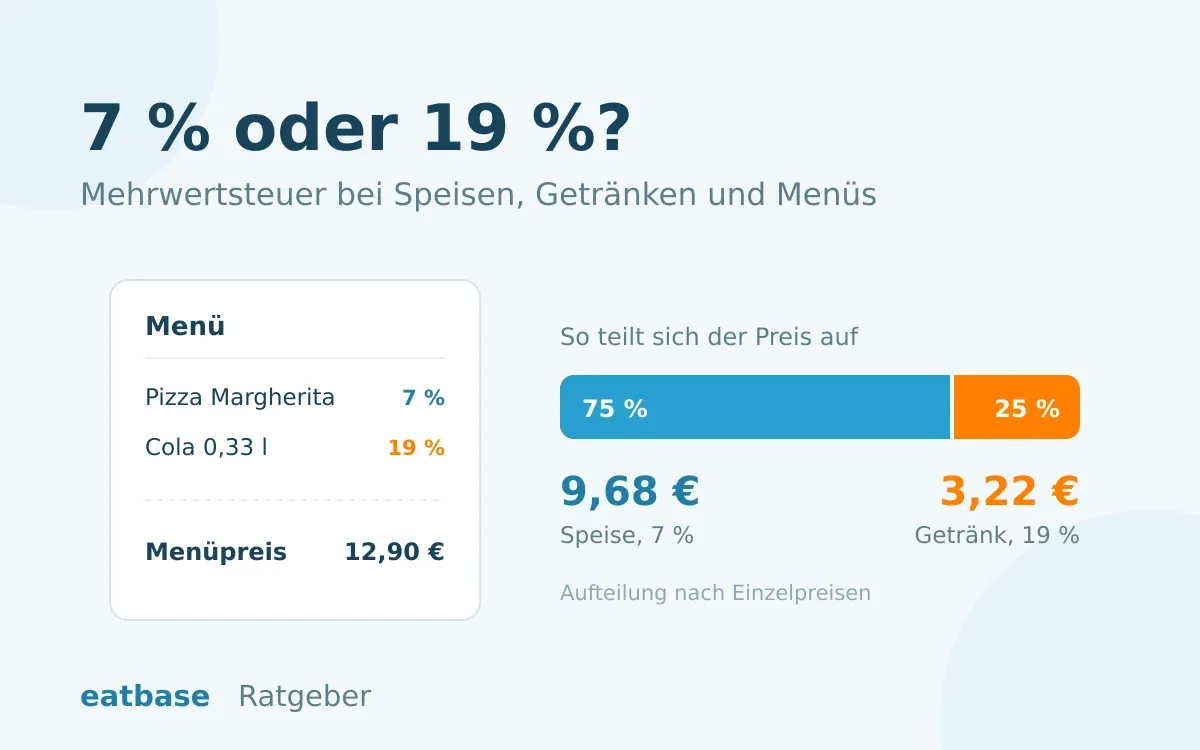
An example: the menu costs 12,90 €. On its own, the pizza costs 10,50 € and the cola 3,50 €, together 14,00 €. The pizza makes up 75 % of that.
| Item | Individual price | Share of the menu price |
|---|---|---|
| Pizza (7 %) | 10,50 € | 9,68 € |
| Cola (19 %) | 3,50 € | 3,22 € |
| Total | 14,00 € | 12,90 € |
The 9,68 € contains 0,63 € VAT, and the 3,22 € contains 0,51 €. That makes 1,14 € in total.
If you had booked the whole menu at 7 %, it would only have been 0,84 €. That is 30 cents too little per menu. With 200 menus a month, 720 € of VAT is missing at the end of the year, and the tax office will claim it back in an audit.
You don’t have to work this out by hand. Our free set menu VAT calculator splits every menu price by individual prices, accurate to the cent and with the values for your till.
BFH XI R 19/23: the burger may not cost more in the menu
For years, many quick-service and chain restaurants calculated differently, namely by the cost of goods. This so-called food and paper method looks at what the ingredients cost to buy. Because drinks are cheap to buy, a smaller part of the menu price usually ends up at 19 %. That lowers the tax.
In its ruling of 22 January 2025 (XI R 19/23), the Federal Fiscal Court rejected this method in the case it decided. The core point, as the court summed it up in its press release of 5 June 2025: the burger in a value meal cannot cost more than the burger sold on its own. A method that assigns a component a larger share of the menu price than it costs on its own is not appropriate. On the same day, the BFH also refused to accept a similar method in a second case (XI R 22/22).
Important for you: the BFH does not rule out other methods completely. You may split differently if your method is at least as appropriate as splitting by individual selling prices. But that is a high bar. For most restaurants, splitting by individual prices is the simplest and safest way. If you want to calculate differently, agree it with your tax adviser first.
Buffet, brunch and all-inclusive: the 30 % rule
Since 2026 there has been a simplification for package offers. In a letter dated 22 December 2025, the Federal Ministry of Finance (Bundesfinanzministerium) added a new paragraph 12 to section 10.1 UStAE. Under it, the tax office will not object if, for combined offers of food including drinks, the drinks share is set at 30 % of the package price. The letter names buffets and all-inclusive offers as examples.
An example: your Sunday brunch costs 39 € per person, including coffee, juice and a glass of sparkling wine.
| Part | Share | of which VAT |
|---|---|---|
| Drinks (30 %, 19 %) | 11,70 € | 1,87 € |
| Food (70 %, 7 %) | 27,30 € | 1,79 € |
| Total | 39,00 € | 3,66 € |
The rule is an option, not an obligation. If your guests usually drink little at the buffet, an exact split can be cheaper. Your tax adviser can work this out with you.
It is still open how far the 30 % rule reaches. The wording talks about combined offers in general, but the examples are buffets and all-inclusive. The letter does not say explicitly whether the flat rate also applies to a classic set menu whose parts are also on your menu individually. For such menus, splitting by individual selling prices remains the safe way.
What this means for your till and online orders
The tax is only correct if it is set up correctly in the system. Go through these points once:
- Check the tax rate for each item. A classic: a drinks category is set to 7 % by mistake. Nobody notices in daily business, but in an audit it shows up straight away.
- Set up menus as components. The till must know which part of the menu price falls under which rate. A menu as one item at 7 % is wrong as soon as a drink is included.
- Keep individual prices up to date. The split depends on the individual prices. If you raise the price of the cola, the split within the menu changes too.
- Separate milk drinks by order type. If you sell milk drinks with at least 75 % milk, you need different rates for eating in and takeaway.
- Check your receipts. The amounts per tax rate should be shown separately on the receipt. Print a receipt with a menu once and check the numbers.
How we handle this at eatbase
In the eatbase ordering system you set the tax rate per category, for example 7 % for pizza and 19 % for drinks. The receipt shows VAT separately by rate, and the monthly report shows your sales at 7 % and 19 % for your tax adviser. If you use a ready2order till, the POS integration can book your online orders automatically with the VAT already split.
You don’t need an ordering system to split your menu prices. The menu calculator is free, needs no sign-up and only calculates in your browser.
Frequently asked questions
Does the reduced rate also apply to delivery and catering? Yes. Since 1 January 2026, food is taxed at a flat 7 %, whether eaten on site, picked up or delivered. According to the Darmstadt Chamber of Commerce (IHK Darmstadt), catering also falls under the reduced rate. Drinks stay at 19 % in all cases, with the exceptions for milk drinks and tap water for takeaway.
Do I have to lower my prices? No, there is no obligation to do so. You decide yourself how you set your gross prices. Still, you should check that your menu, website and till show the same prices everywhere.
Is the cut to 7 % temporary? The law does not include an end date. As with any tax rule, lawmakers can change it. This article reflects the situation as of October 2026.
Can I split by cost of goods? Only if your method is at least as appropriate as splitting by individual selling prices. No component may get a larger share of the menu price than it costs on its own. The Federal Fiscal Court rejected the food and paper method in two cases in January 2025. We would advise against it unless you have agreed it with your tax adviser.
What do I do if the menu costs more than the individual prices added together? This rarely happens, for example with a menu that includes an extra service. Then every component would be above its individual price, and the standard calculation no longer works. In this case, clarify the split with your tax adviser.
Does the 30 % rule also apply to my lunch special with a drink? This is not clearly regulated. The letter from the Federal Ministry of Finance (BMF) names buffets and all-inclusive as examples. For a menu whose parts are also on the menu individually, splitting by individual selling prices is the safe way.
Conclusion
Food 7 %, drinks 19 %, and set menus are split by individual prices. If you stick to this and check the tax rates in your till properly once, you are on the safe side. For buffets and package offers, the 30 % gives you a simple alternative.
This article reflects the legal situation as of October 2026 and is not tax advice. What is binding for your business is what you agree with your tax adviser and your tax office.